ETF Overlap: Are You Diversifying or Buying the Same Risk?
Adding an ETF can broaden a portfolio, create a deliberate tilt, or simply give existing exposure another ticker. The fund count will not tell you which has happened. The holdings and weights will.
By Jyoung Ahn · October 5, 2026
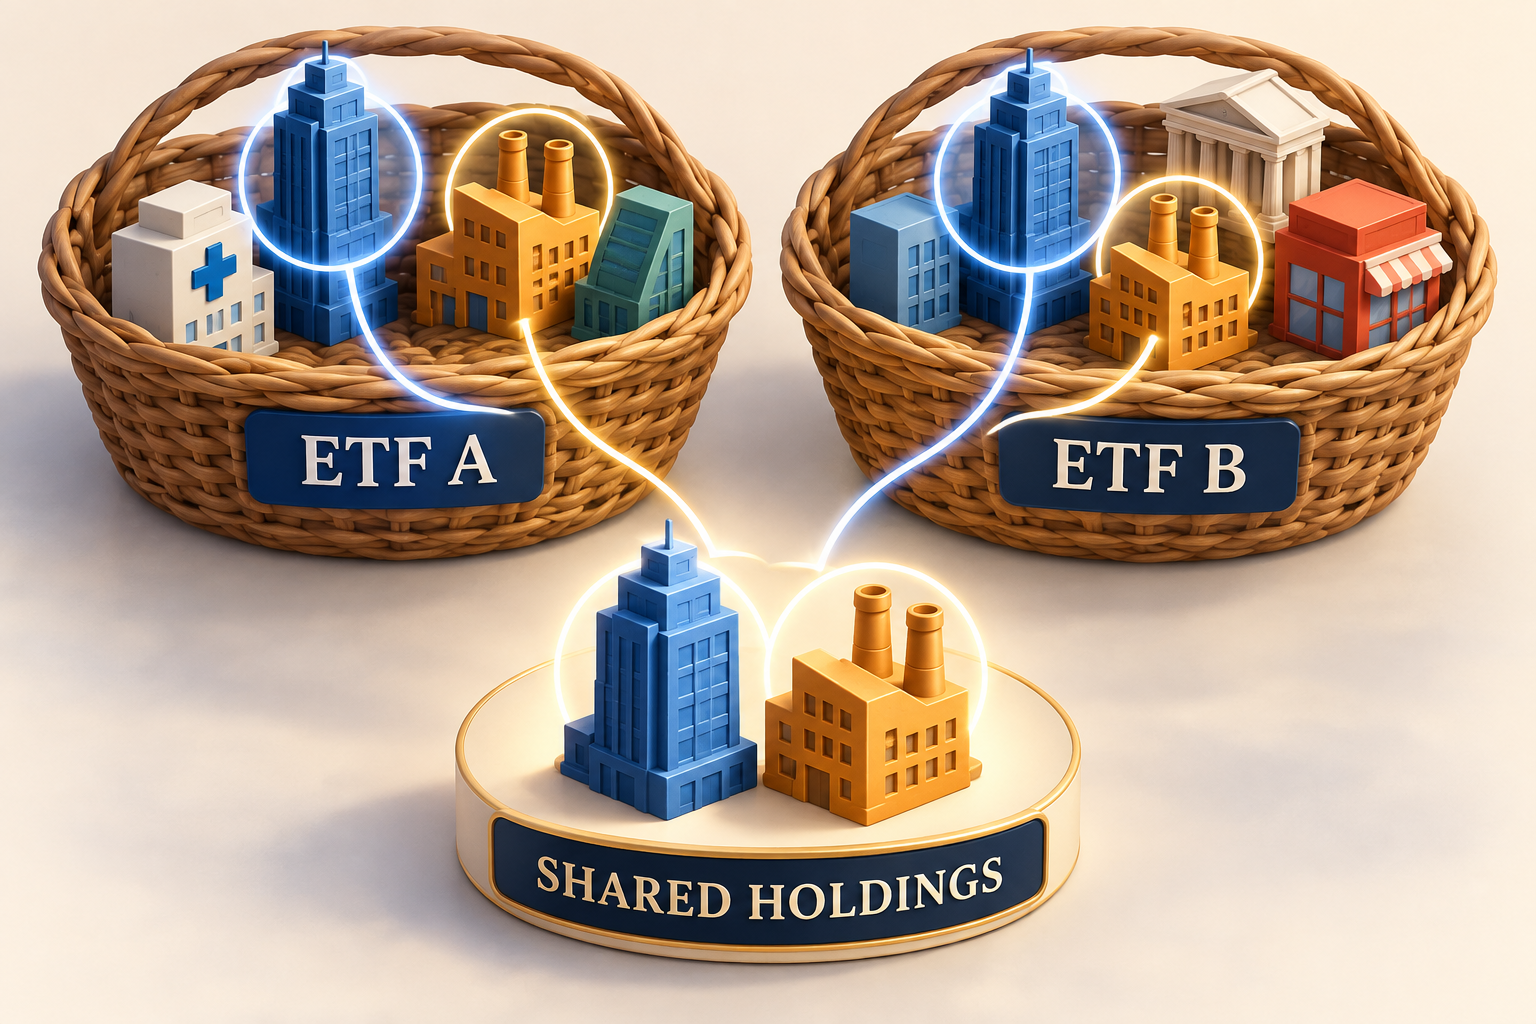
It is easy to mistake a longer list of funds for a more diversified portfolio. A broad-market ETF is joined by a growth fund, a technology fund, and a thematic fund. The account statement looks increasingly sophisticated. Underneath the labels, however, more of the money may depend on the same companies or economic forces.
The opposite mistake is to treat every shared holding as a defect. Overlap can be intentional. An investor may want a particular tilt and use a second ETF to create it. The problem is not repetition by itself; it is repetition that the investor has not measured or chosen.
Our first column on ETF investing myths challenged the assumption that more funds automatically provide more diversification. This article explains how to test an addition before buying it. The relevant unit is not the ticker. It is the resulting portfolio exposure.
1. What should the new fund change?
A prospective holding should solve an identifiable problem or express an intentional preference. It might broaden an asset-class allocation, change a geographic exposure, supply a particular equity style, or alter a cash-flow pattern. “It is highly rated” and “its chart looks strong” do not specify what the portfolio needs.
Write the proposed change in plain English: “This would reduce my dependence on a narrow group of companies,” or “This would deliberately increase my exposure to dividend-oriented businesses.” Those are different objectives. The first concerns diversification; the second concerns a tilt that may or may not improve diversification in the existing portfolio.
As our VOO versus SCHD comparison illustrates, different selection rules can create different sector weights while both strategies remain U.S. equities. A changed distribution pattern is not proof that the portfolio has gained a new source of protection.
2. Turn fund holdings into portfolio exposure
To estimate exposure to a particular company in a conventional stock-fund portfolio, multiply each fund’s share of your portfolio by the company’s weight inside that fund. Add those contributions across the funds, then include any direct holding of the company.
Use decimals in the calculation: 20% is 0.20, not 20. If a fund represents 20% of your portfolio and holds 40% of its assets in Company X, that fund contributes 8% of the portfolio’s exposure to X. The fund’s company weight and your portfolio’s company weight answer different questions.
The arithmetic below uses deliberately small, fictional stock funds so the whole example can be inspected. It is not a representation of any actual ETF, and such concentrated toy portfolios are not suggested investments.
| Fictional company | Inside Fund A | Inside Fund B | Portfolio: 80% A, 20% B |
|---|---|---|---|
| X | 20% | 40% | 24% |
| Y | 30% | 50% | 34% |
| Z | 50% | 0% | 40% |
| W | 0% | 10% | 2% |
| Total | 100% | 100% | 100% |
On a small screen, swipe the table sideways. The combined-portfolio results are also shown in the cards below.
Assume the investor moves from 100% Fund A to 80% Fund A and 20% Fund B, with no other assets. Company X exposure becomes (0.80 × 0.20) + (0.20 × 0.40) = 0.24, or 24%. Company W is a genuinely new holding, but its 10% weight inside B translates to only 2% of the combined portfolio.
Before · 100% Fund A
X: 20%
Y: 30%
Z: 50%
W: 0%
After · 80% A + 20% B
X: 24%
Y: 34%
Z: 40%
W: 2%
Fictional stock funds. Each circular chart sums to 100%. Labels give the exact weights, including W’s small 2% slice. This is an exposure calculation—not actual ETF holdings or a forecast of overall risk.
The addition increases the number of companies from three to four. It reduces exposure to Z. At the same time, combined exposure to X and Y rises from 50% to 58%. It has changed concentration in more than one direction. Calling it simply “more diversified” hides the trade-off.
These figures cannot determine whether risk has improved overall. That would also depend on the companies’ characteristics and how their returns move together. The example demonstrates an exposure calculation, not a statistical model of portfolio risk.
3. Look beyond shared company names
Two funds can hold different companies that depend on the same economic driver. A pair of businesses may both be sensitive to similar spending cycles, financing conditions, or end customers. Conversely, funds holding some of the same names can have substantially different weights and different rules for maintaining them.
Review exposure in layers: companies, sectors, geography, asset classes, and investment style. For fixed income, credit quality and interest-rate sensitivity also matter. A portfolio of several bond funds can repeat a duration or credit bet just as a portfolio of several stock funds can repeat a sector bet.
FINRA’s concentration-risk guidance explicitly encourages investors to examine underlying fund positions and overlapping individual holdings. Investor.gov likewise cautions that several funds do not necessarily provide the diversification an investor expects.
A holdings-overlap percentage is therefore a useful diagnostic, not a verdict. Understand whether a tool counts shared names, compares their weights, or uses a different definition. Two numbers labeled “overlap” can describe different things. Neither is a probability of loss or a complete assessment of diversification.
4. The size and source of new money matter
“Add a fund” is incomplete until you specify how it is funded. Selling part of one holding to buy another changes exposures differently from contributing new cash. A small purchase may change the fund count while barely changing the underlying portfolio.
Suppose instead that an investor has $80,000 in Fund A and contributes $20,000 to Fund B. The resulting weights are also 80% and 20%, so the same look-through arithmetic applies. The source of funding differs, and so may taxes and trading costs, but the final exposure calculation follows the final dollar amounts.
If the contribution were only $1,000, Fund B would represent about 1.23% of the $81,000 portfolio. Its 10% allocation to W would then create roughly 0.12% portfolio exposure to W. A fourth company would appear on the look-through list, but the investor would still have very little money in it. Counting names would greatly overstate the scale of the change.
For an investor trying to correct concentration, this distinction is central. The question is how much exposure actually moves—not how many additional positions appear in the account.
5. Decide which overlaps are intentional
A broad equity foundation plus a smaller style allocation can be coherent. The investor knowingly accepts additional exposure to particular characteristics, documents the intended size, and evaluates that choice against the rest of the portfolio. A low-overlap target is not a substitute for that reasoning.
Duplicating essentially the same exposure across two vehicles may also reflect an operational preference, but it should not be described as a major improvement in investment diversification. Multiple providers do not, by themselves, transform the underlying market risk.
Equally, an ETF with little holdings overlap may add risks the investor does not want. A narrow theme, unfamiliar market, or complex strategy can make a ticker list look different without making the portfolio more suitable. Novelty is not the objective. A better match between exposure and purpose is.
6. Review the portfolio before and after
A practical review does not require constant portfolio monitoring. It requires a consistent set of inputs when making a material change. Begin with current dollar values, use provider holdings from reasonably comparable dates, and distinguish a quick top-holdings check from a comprehensive analysis.
The ten largest positions can reveal an obvious concentration, but they cannot establish full overlap across hundreds of holdings. For a detailed calculation, reconcile complete holdings, duplicate share classes, cash, and fund-of-fund positions where relevant. For leveraged or derivatives-based strategies, simple market-value weights may not capture the economic exposure; read the strategy documents instead of forcing them into a plain-stock worksheet.
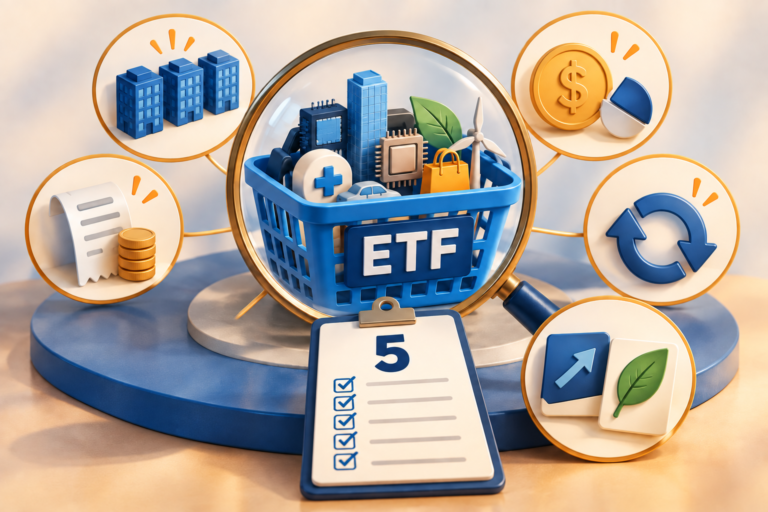
1 Purpose
What specific portfolio problem will the new fund solve?
2 Exposure
What companies, sectors, or risks will increase or decrease?
3 Funding
Will you sell an existing holding or contribute new cash?
4 Implementation
What costs, tax consequences, and ongoing work come with the change?
An editorial worksheet. No universal ETF count or allocation limit is implied.
Record the proposed allocation and what it changes before placing a trade. Include the new fund’s expense ratio, trading considerations, potential tax consequences of any sale, and the effort needed to keep the strategy understandable. An addition should justify its complexity, not merely its purchase price.
After purchase, revisit the explanation at a planned review or when a material change occurs. Market moves, index revisions, and contributions can all alter exposures. A holding that once supplied a modest tilt can become a larger bet without another purchase.
The bottom line: count exposure, not tickers
There is no universally correct ETF count. One fund can already contain many investments; several funds can contain repeated bets. The discipline is to understand the economic exposure, decide which concentrations are intentional, and make additions that serve a stated purpose.
Before buying another ETF, finish this sentence: “After this purchase, my portfolio will have more of ___ and less of ___, and that change serves ___.” If the blanks cannot be filled with something more concrete than a new ticker, the research is not finished.
Sources and calculation notes
- FINRA: Concentrate on Concentration Risk.
- SEC Investor.gov: Asset Allocation and Diversification.
- FINRA: Exchange-Traded Funds and Products—product differences, exposure overlap, and trading considerations.
Sources reviewed October 5, 2026. All fund and company weights in the worked examples are fictional. The $1,000 contribution example uses B’s weight of $1,000 ÷ $81,000 ≈ 1.2346%; W’s portfolio exposure is that weight × 10% ≈ 0.1235%. No outside data or actual ETF holdings enter those calculations.
Educational information, not personalized investment or tax advice. Diversification does not guarantee a profit or prevent losses. The framework is editorial analysis, not a recommendation to buy or sell any particular fund.