ETF Rebalancing vs. Replacing a Fund: Solve the Right Problem
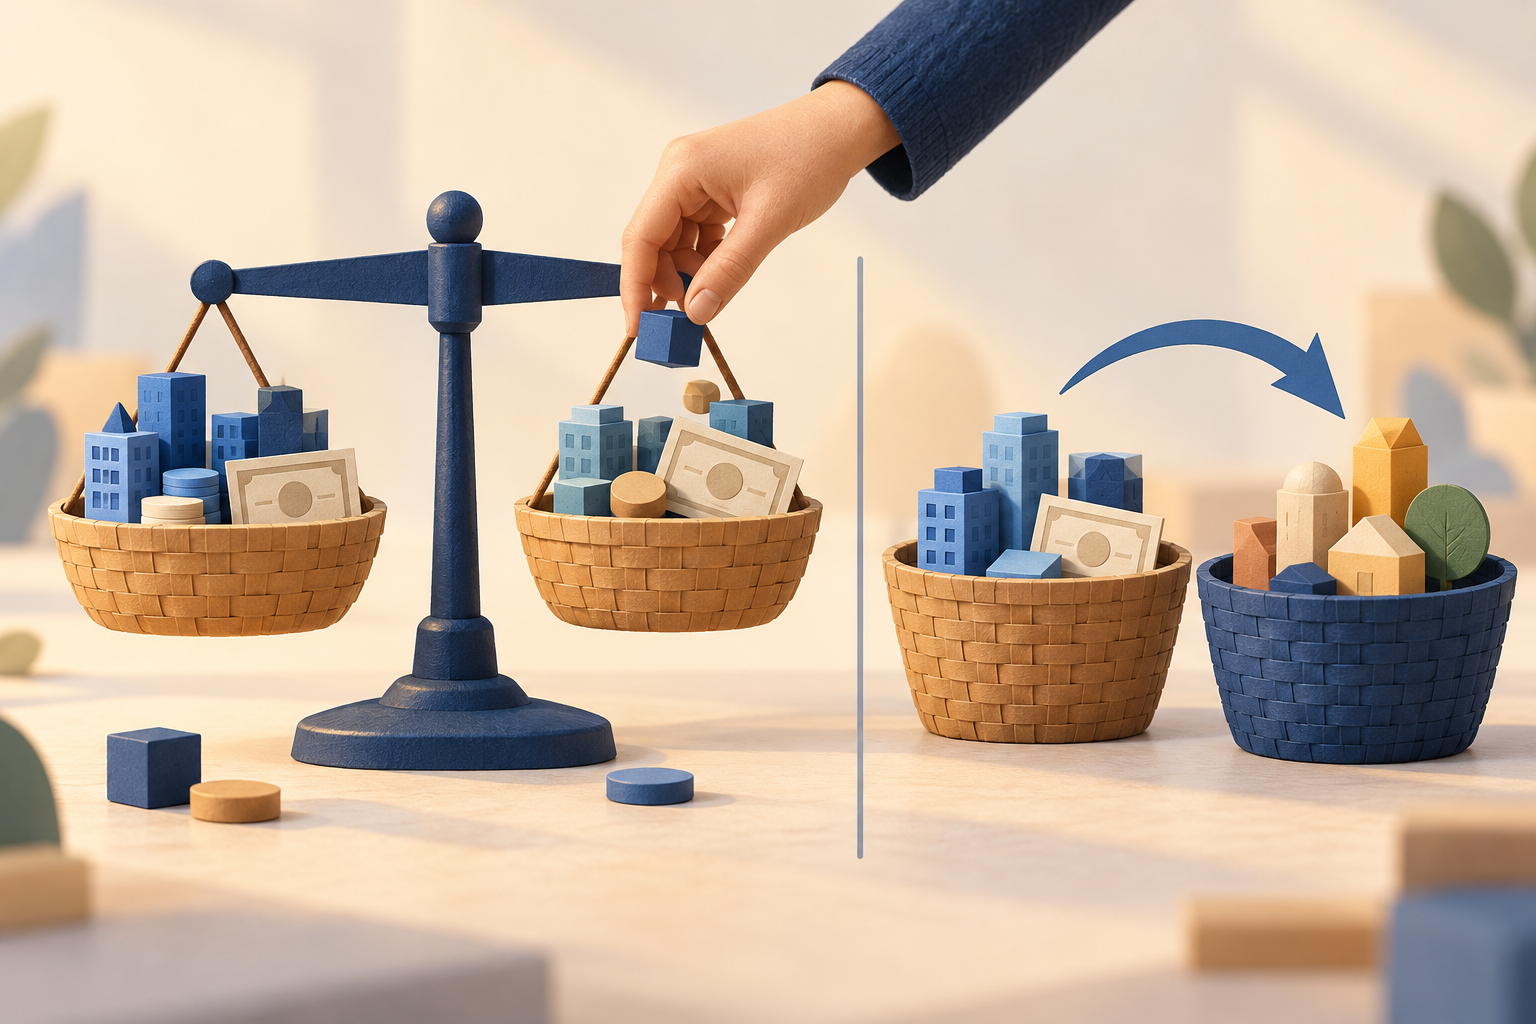
Rebalancing changes how much you hold. Replacing an ETF changes what you hold. Redesigning a portfolio changes the plan itself. Diagnose the problem before choosing a transaction—and compare contributions, distributions, sales, and their costs before acting.
A stock ETF has climbed, and its weight in your portfolio is now larger than you intended. You open a research page and start looking for a better fund. That is a plausible response to the wrong question: the product may still be doing its job. Your exposure to it may be the part that needs attention.
The reverse mistake is possible, too. A fund changes its strategy, yet an investor treats the issue as a routine percentage adjustment. Restoring the old weight will not restore the old investment mandate.
This report separates three decisions: restoring an allocation, investigating a replacement, and revising the allocation itself. It builds on giving stocks, bonds, and cash different jobs. The examples are hypothetical, not recommended allocations or actual ETF performance. The representative image is an AI-generated conceptual illustration, not a depiction of real fund holdings.
1. Name the problem before naming a trade
A target allocation is a statement about the risks and responsibilities you intend to carry. A current allocation is a measurement. The difference between them is useful only if the target still makes sense. A calendar reminder can initiate a review; it cannot tell you whether a household’s circumstances have changed.
Allocation drift
Question: Is the current weight outside the range I planned to tolerate?
The fund’s role and your objective may be unchanged. Research ways to restore the intended exposure rather than assuming a new ticker is needed.
A product-role mismatch
Question: Has the fund’s mandate, underlying exposure, implementation, or cost changed in a way that matters to its assigned job?
Inspect official documents and effective dates. Investigate alternatives performing that same job, including the costs of moving between them.
A changed investor need
Question: Has the time until you need the money, spending requirement, or capacity to absorb losses changed?
Reconsider the plan before restoring an old target. A once-reasonable allocation is not a permanent obligation.
Recent disappointment is a prompt to investigate, not a diagnosis. A strategy can lag while behaving as described. Conversely, a strong recent return does not establish that a changed strategy still fits your intended role. Compare the fund with the job you assigned it, not just with whichever chart currently looks best.
2. Compare routes, not just funds
For an allocation that remains appropriate, there may be several routes toward the target. The SEC’s asset-allocation guide describes selling overweight assets, buying underweight assets, and changing the direction of ongoing contributions. Those are implementation choices—not promises of higher returns.
Available cash flows matter. New savings can go to an underweight category. Cash distributions can be reviewed for the same purpose when they are not needed for spending. That does not make them free money: a distribution is part of the investment’s economics, not an extra return to count twice.
Sales can adjust weights more quickly than a small contribution. They can also realize gains or losses and introduce trading frictions. Waiting for contributions avoids a sale only if the available cash and timing are sufficient; it leaves the portfolio exposed to its current mix in the meantime.
3. Check the denominator: $12,000 and $20,000 solve different problems
Consider a hypothetical $120,000 portfolio with $84,000 in stocks and $36,000 in bonds. Its current mix is 70% stocks and 30% bonds. For this illustration only, assume a still-valid target of 60% stocks and 40% bonds.
| Route | Stocks | Bonds | Total | Stock weight |
|---|---|---|---|---|
| Starting point | $84,000 | $36,000 | $120,000 | 70.0% |
| Move $12,000 from stocks to bonds | $72,000 | $48,000 | $120,000 | 60.0% |
| Add $20,000 to bonds; no stock sale | $84,000 | $56,000 | $140,000 | 60.0% |
| Add only $5,000 to bonds | $84,000 | $41,000 | $125,000 | 67.2% |
On a narrow screen, scroll within the table. These are hypothetical accounting examples. They exclude price changes during implementation, taxes, bid–ask spreads, commissions, and withdrawals. No cash reserve is modeled. The percentages are not recommendations.
Target stocks = $120,000 × 0.60 = $72,000
Amount shifted = $84,000 − $72,000 = $12,000
Route B · keep stocks constant, add new money
$84,000 ÷ ($120,000 + X) = 0.60
X = ($84,000 ÷ 0.60) − $120,000 = $20,000
The difference is the denominator. A transfer between existing holdings leaves the modeled total unchanged. A contribution increases it. Saying “put the $12,000 shortfall into bonds” confuses those two operations: adding $12,000 would produce $84,000 ÷ $132,000, or approximately 63.6% stocks, not 60%.
A $5,000 contribution still moves the mix toward the illustrative target. It simply does not complete the adjustment. That distinction helps you write an honest implementation plan: partial progress, remaining exposure, and the next review—not a claim that any contribution automatically restores balance. If spending removes cash or prices move, recalculate the total.
4. When replacement deserves its own research
Changing the ETF may be reasonable when the current fund no longer supplies the exposure or implementation you intended. Begin with the official mandate and index methodology, not a marketing label. Compare relevant risks, concentration, tracking behavior, trading conditions, and ongoing fund costs. A small difference in one field does not settle the whole decision.
Look through the new fund as well. FINRA’s concentration guidance highlights overlap among funds and direct holdings. Replacing one stock ETF with another can leave the same underlying concentration largely intact, even when the names or providers differ.
Capital growth is an objective, not necessarily a growth-stock style. A dividend-oriented equity ETF can still be part of the stock allocation. Buying more of it does not create a bond or a cash reserve. For a household pursuing current income, investigate distribution sources and variability alongside the timing of spending and remaining capital. Dividend growth, high dividend yield, and option-based income should not be treated as interchangeable roles.
Personality affects implementation, but it does not decide product suitability. Frequent price checking may call for a written review process. It does not establish that a dividend fund is safer for you, or that a more patient investor can afford unlimited equity risk.
5. Check the account and implementation before executing
A sensible portfolio idea can have an expensive implementation. List the account involved, possible realized gains or losses, bid–ask spread, commissions where applicable, and any restrictions. Tax treatment differs across taxable and tax-advantaged accounts; this report does not calculate a household’s tax liability.
For U.S. taxable investing, a loss sale followed by a purchase is not automatically a usable tax deduction. IRS Publication 550 (2025), under “Wash Sales,” describes loss-sale restrictions involving substantially identical securities acquired within 30 days before or after the sale. A different ticker alone is not a tax-safety determination. The publication also addresses IRA or Roth IRA acquisitions. Seek qualified advice when account interactions or substantial losses matter.
That paragraph is a caution, not a tax-loss-harvesting strategy or an ETF-pair ruling. The edition checked is 2025; no 2026 tax rate or contribution limit is asserted here.
6. Leave a decision record that survives the next headline
Use the following sequence as an editorial review map—not an automated trade instruction:
- Has my objective changed?
If yes, review the target and spending plan first. If no, keep the target as the reference for the next question. - Does the fund still perform its assigned role?
If uncertain, open the mandate, index, and risk disclosures. Investigate replacement separately from weight adjustment. - Is there meaningful allocation drift?
If yes, compare cash flows and transactions using the same current portfolio total. If no, a review can end without a trade. - Is the proposed route workable after costs and account conditions?
Record the remaining uncertainty, implementation constraints, and the next review condition before deciding.
A compact record needs five items: the problem, the still-valid target or reason to revisit it, the evidence, the alternatives considered, and the reason for the chosen action or non-action. Keep the previous record. When evidence changes, append what changed rather than rewriting the past as if you had always known it.
The aim is not a permanently tidy percentage. It is a portfolio whose risks remain intentional. Sometimes that requires restoring a weight. Sometimes it requires a different fund—or a different plan. Knowing which problem you are solving is the work that comes before the order.
Sources and scope
- SEC: Beginner’s Guide to Asset Allocation, Diversification, and Rebalancing, March 2011, printed page 5: rebalancing routes and review approaches. Educational principles, not current market data.
- FINRA: Concentrate on Concentration Risk, June 15, 2022: concentration and look-through review.
- IRS Publication 550 (2025), Chapter 4, Wash Sales: U.S. tax caution. These sources were accessed October 23, 2026.
Educational analysis, not individualized investment, tax, or trading advice. All dollar examples are fictional. No specific ETF purchase, replacement, target allocation, return forecast, or tax outcome is recommended. Illustrations are conceptual and AI-generated.